Calculate PM Awas Yojana Urban 2.0 ISS Subsidy
Loans up to ₹25 lakh, but the subsidy is worked out only on the first ₹8 lakh
Your estimated subsidy
LIGThis is only an estimate. The actual subsidy is decided after the bank checks and approves your case.
Where to find the official ISS subsidy calculator and how to use it
On the official scheme website, pmaymis.gov.in, there’s a calculator called “ISS Subsidy Calculator” under Citizen Services in the top menu. It asks for five things:
- Annual Family Income: the whole family’s yearly income. This decides your category: up to ₹3 lakh is EWS, ₹3 to 6 lakh is LIG and ₹6 to 9 lakh is MIG.
- Loan Amount: the full home loan amount.
- Tenure (Months): the loan tenure in months. For a 10-year loan, enter 120.
- Is this your First Pucca House?: choose “Yes” if this is the family’s first pucca house.
- Carpet Area (Sq M): the carpet area of the house in square metres, which must be up to 120.
As soon as you fill it in, “Scheme Details” on the right shows three things: your category (Category), the total subsidy (Subsidy Amount Actual) and each year’s instalment (Subsidy Amount Annually). For example, with ₹9 lakh income, an ₹8 lakh loan and a 72-month tenure, it looks something like this:
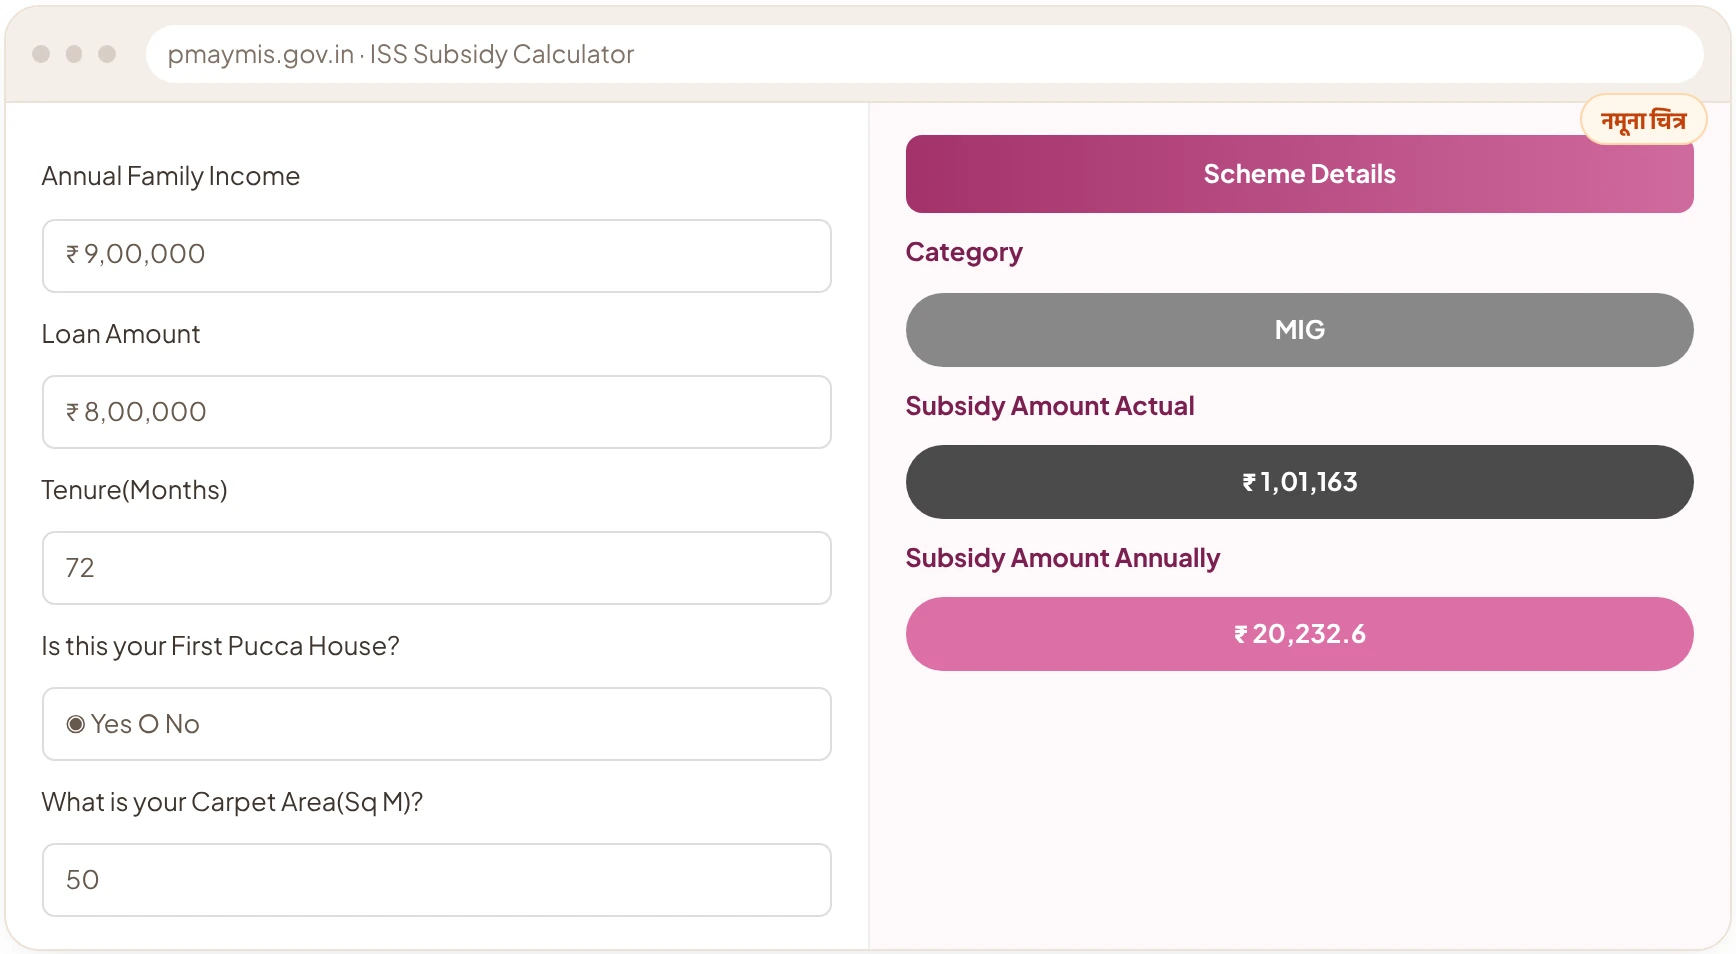
Here the total subsidy is ₹1,01,163, and a fifth of that, ₹20,232.6, is each year’s instalment. The calculator above gives the same figure for this example.
How the ISS subsidy is calculated
According to the ISS page on the official scheme website, ISS gives a 4% interest subsidy on the first ₹8 lakh of a home loan, for a tenure of up to 12 years, up to a maximum of ₹1.80 lakh. In simple terms, the sum works like this:
So the longer the loan, the bigger the subsidy, until it reaches the ₹1.80 lakh limit. Borrowing more than ₹8 lakh doesn’t raise the subsidy. Some examples:
| Home loan | Tenure | Total subsidy | Each year |
|---|---|---|---|
| ₹3 lakh | 8 years | ₹51,051 | ₹10,210 |
| ₹5 lakh | 10 years | ₹1,07,471 | ₹21,494 |
| ₹8 lakh | 6 years | ₹1,01,163 | ₹20,233 |
| ₹8 lakh | 8 years | ₹1,36,136 | ₹27,227 |
| ₹8 lakh | 10 years | ₹1,71,953 | ₹34,391 |
| ₹8 lakh or more | 12 years or more | ₹1,80,000 | ₹36,000 |
In the last row the sum goes above ₹1.80 lakh, so the limit kicks in. The guidelines put this ₹1.80 lakh at ₹1.50 lakh in today’s money (NPV at an 8.5% discount rate), which is why you’ll also see ₹1.50 lakh in many places. See the full ISS working for a ₹20 lakh home loan.
Who gets the ISS subsidy?
Seeing a figure in the calculator isn’t enough. You only get the subsidy when all of these conditions are met:
| Condition | Limit | ||
|---|---|---|---|
| Family’s yearly income | Up to ₹9 lakh (EWS up to ₹3 lakh, LIG up to ₹6 lakh, MIG up to ₹9 lakh) | ||
| Home loan | Up to ₹25 lakh, with a tenure of more than 5 years | ||
| House price | Up to ₹35 lakh | ||
| House size | Up to 120 sq m carpet area | ||
| Pucca house | The family must not own a pucca house anywhere in India | ||
| When the loan was sanctioned | On or after 1 September 2024 | ||
Loans taken to buy, re-purchase or build a house can get the subsidy. You have to give the bank proof of income.
When and how the subsidy is paid
The subsidy doesn’t come to you in cash. It is credited straight to your home loan account in 5 yearly instalments, which brings down what you owe on the loan:
- 1st1/5 of the total
- 2nd1/5 of the total
- 3rd1/5 of the total
- 4th1/5 of the total
- 5th1/5 of the total
Each instalment comes only if the loan is still running and more than half of the principal is still outstanding. So if you repay the loan early, or pay back more than half the principal, the remaining instalments can stop.
How to apply: You get ISS through your bank or housing finance company. When you take the loan, tell the bank you want the PM Awas Yojana Urban 2.0 interest subsidy. You can also apply for ISS yourself on the official scheme website. The full process is in how to apply online for PM Awas Yojana Urban 2.0.
Common questions about the ISS subsidy
How much subsidy does PM Awas Yojana Urban 2.0 give on a home loan?
ISS gives a subsidy equal to 4% interest on the first ₹8 lakh of a home loan, for a tenure of up to 12 years. The maximum subsidy is ₹1.80 lakh. The actual amount depends on your loan amount and tenure.
Where can I find the ISS subsidy calculator?
The menu on the official scheme website, pmaymis.gov.in, has an “ISS Subsidy Calculator” under Citizen Services. This page also has a calculator that works it out the same way.
How much subsidy will I get on a ₹20 lakh home loan?
The subsidy is worked out only on the first ₹8 lakh of the loan, so even for a ₹20 lakh loan the sum is done on ₹8 lakh. With a tenure of 12 years or more it reaches ₹1.80 lakh; with 10 years it’s about ₹1.72 lakh.
Is the ISS subsidy paid in one go or in instalments?
The subsidy comes in 5 equal yearly instalments, straight into your home loan account. Each instalment comes only if the loan is still running and more than half of the principal is outstanding.
Do families earning more than ₹9 lakh get the ISS subsidy?
No. ISS is only for families earning up to ₹9 lakh a year: EWS up to ₹3 lakh, LIG up to ₹6 lakh and MIG up to ₹9 lakh.
Awas Score
Will your family’s turn come under this scheme?
Find out your family’s Awas Score in 2 minutes.
Get my Awas Score